All 23 banks operating in Ghana have met the Bank of Ghana’s regulatory capital requirements, marking a significant milestone in the recovery of the banking sector following the economic crisis and the Domestic Debt Exchange Programme (DDEP).
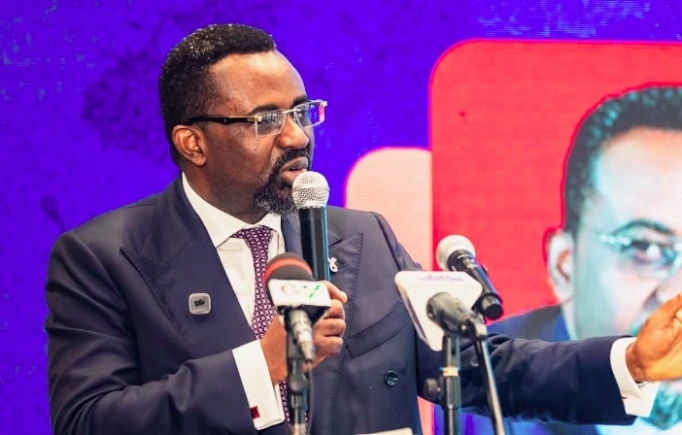
Governor of the Bank of Ghana, Dr Johnson Pandit Asiama, disclosed this at the 43rd Annual General Meeting of the Ghana Association of Banks and the launch of the sixth edition of the GH Bankers’ Voice magazine in Accra on Thursday, October 8, 2026.
According to the Governor, the 2022 audited financial statements showed that 13 banks had breached regulatory capital requirements following the economic crisis and impairments to financial assets.
He attributed the sector’s recovery to collective efforts by banks, shareholders, investors, the Ghana Association of Banks, the government and the central bank.
“Through the collective efforts of banks, shareholders, investors, the Association, Government and the Bank of Ghana, all 23 banks have now met the regulatory capital requirements. This is a significant achievement,” he said.
Here is how Ghana’s banking sector has worked towards restoring its financial strength and improving its resilience.
1. Banks, Investors and Government Worked Together to Restore Capital
The recovery involved concerted efforts by financial institutions, their shareholders and investors, supported by the government, the Ghana Association of Banks and the Bank of Ghana.
These efforts helped banks address capital shortfalls that emerged following the economic crisis and financial asset impairments associated with the period surrounding the Domestic Debt Exchange Programme.
With all 23 banks now meeting the regulatory requirements, the central bank says the focus must shift from restoring capital to ensuring that institutions maintain adequate buffers against future shocks.
2. Stronger Macroeconomic Conditions Supported Sector Growth
Dr Asiama said the banking sector had recorded significant improvements since 2025, supported by better macroeconomic conditions and continued regulatory and supervisory reforms.
By the end of August 2026, total banking sector assets had risen by 20.47 per cent to GH¢500.20 billion, up from GH¢415.20 billion a year earlier.
The sector’s Capital Adequacy Ratio also improved from 18.28 per cent to 19.10 per cent, comfortably above the regulatory minimum of 13 per cent.
These figures indicate stronger balance sheets, although the Governor cautioned that improved financial indicators must translate into sustainable business models, stronger risk management and greater support for productive economic activity.
3. The Bank of Ghana Reviewed Banks’ Business Models
In 2025, the central bank conducted a comprehensive thematic review of the viability and long-term sustainability of banks’ business models.
The exercise identified vulnerabilities that were subsequently shared with the affected institutions. Engagements with their boards and senior management have since commenced.
The Bank plans to conduct a second round of Business Model Analysis in 2027 to assess how banks are positioned to remain sustainable and manage the risks embedded in their operations.
Dr Asiama stressed that boards and senior management must understand the risks associated with their institutions’ business models and ensure that capital levels reflect their respective risk profiles.
4. Banks Are Under Pressure to Reduce Non-Performing Loans
Improving asset quality has been another important part of the sector’s recovery.
The banking industry’s Non-Performing Loans (NPL) ratio fell from 20.77 per cent in August 2025 to 15.66 per cent in August 2026.
Despite the improvement, the ratio remains above the Bank of Ghana’s prudential limit of 10 per cent, which banks are required to meet by the end of December 2026.
To address the problem, the central bank issued its Notice on Non-Performing Loans in August 2025 to strengthen credit-risk governance, establish prudential limits and provide remedial measures for wilful defaulters.
Banks have also been urged to improve credit assessments, loan monitoring, collateral management, restructuring, write-offs and recovery processes.
The Bank is preparing a Directive on Credit Risk Management to complement the existing NPL Notice.
5. New Liquidity Rules Are Being Introduced
The Bank of Ghana is also working to strengthen banks’ ability to meet their financial obligations during periods of stress.
Dr Asiama said the central bank was preparing to publish the Liquidity Coverage Ratio Directive, which will establish prudential liquidity requirements for banks.
The proposed framework is expected to reinforce liquidity risk management and encourage institutions to maintain appropriate contingency funding arrangements, diversify their funding sources and improve asset-liability management.
The Governor emphasised that liquidity management should be embedded in banks’ daily operations rather than treated merely as a regulatory compliance exercise.
6. Stress Testing Is Helping Banks Prepare for Future Shocks
The central bank has strengthened its macroprudential stress-testing framework and engaged banks on the results of assessments conducted under severe but plausible economic and financial scenarios.
These exercises help identify potential vulnerabilities and evaluate how well financial institutions could withstand adverse conditions.
Banks are expected to use the findings to inform capital planning, liquidity management, risk appetite and strategic decisions.
The approach is intended to ensure that institutions do not simply meet minimum regulatory requirements but are also adequately prepared for unexpected economic and financial disruptions.
7. Cybersecurity and Digital Risk Management Are Receiving Greater Attention
As digital financial services expand, the Bank of Ghana is increasing its supervisory focus on cybersecurity, digital fraud, data protection, cloud computing, third-party dependencies and operational resilience.
Following the publication of its revised Cyber and Information Security Directive, the central bank has continued working with the Ghana Association of Banks and other industry stakeholders to support implementation.
The Bank plans to conduct thematic reviews to assess banks’ compliance with the directive.
Dr Asiama said bank boards and senior management must treat cybersecurity and operational resilience as core business risks rather than issues limited to technology departments.
8. The Bank Is Developing Rules for Artificial Intelligence
The central bank is also developing a Directive on the Use of Artificial Intelligence in the Financial Sector.
The proposed directive is intended to encourage responsible innovation while ensuring appropriate governance throughout the AI lifecycle.
Artificial intelligence could improve credit assessments, fraud detection, customer service, risk management and operational efficiency. However, its use also introduces risks involving data quality, model reliability, cybersecurity and consumer protection.
The Bank’s approach seeks to ensure that technological innovation is accompanied by adequate safeguards.
Can Ghana’s Banking Sector Sustain the Recovery?
Although all 23 banks have met regulatory capital requirements, Dr Asiama cautioned that the achievement does not mark the end of the reform process.
He said the priority now is to preserve the gains, strengthen risk management and ensure that banks maintain adequate capital and liquidity buffers while supporting Ghana’s economic development.
The Governor emphasised that regulation alone cannot guarantee a resilient banking sector. Banks’ boards, management teams and institutions must also develop strong risk cultures and sustainable business models.
He said Ghana’s ambition should be to build a banking sector capable of absorbing shocks, adapting to technological change and financing the country’s long-term economic transformation.

